


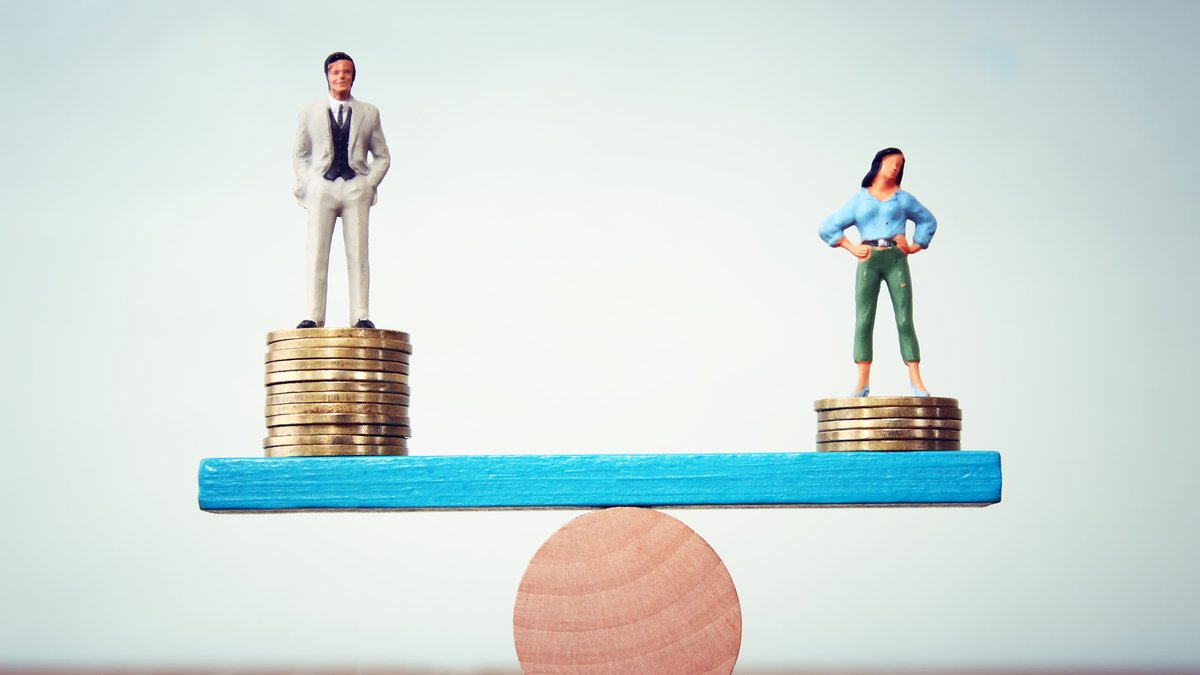
New findings from Scottish Widows indicate the gap between male and female pension incomes has shrunk to £3,800 annually, down from £6,000 in 2025.
Women’s expected median retirement income has climbed by £1,500 year-over-year to £14,500 – the highest level since Scottish Widows began tracking these figures three years ago. Despite this improvement, female retirees still lag behind their male counterparts, who are projected to receive £18,300 annually. Just over a quarter (27 per cent) of women are on track for a comfortable retirement. Meanwhile, a third (33 per cent) of women were found to be at risk of retirement poverty, defined in the research as an income of less than £13,900 a year for a single person or £22,500 for a two-person household.
Retirement Income Projections
The company credits this reduction in the gender disparity to narrower pay gaps between men and women, increased state pension benefits, and greater savings accumulation among women. However, significant obstacles to financial security in retirement persist, especially during early career stages.
Barriers to Retirement Savings
Data analysis shows 14 per cent of women under 30 earn below the £10,000 threshold required for automatic pension enrollment, compared with 9 per cent of men, potentially missing out on employer pension contributions and early investment growth.
The research also found that 71 per cent of women aged 22-25 with a Scottish Widows workplace pension contributed 10 per cent or less of their pay, compared with 64 per cent of men. Women were also less likely than men to contribute more than 15 per cent of their earnings across every pay band.
Jill Henderson, Scottish Widows’ retirement expert, welcomed the narrowing gap but stressed that further action was needed to address the inequalities affecting women’s retirement outcomes.
Related Post: Gaps in governance persist between small and large pension schemes
“The fact that the gender pension gap is at its narrowest point since the National Retirement Forecast began is proof that progress is possible,” she said.
“More women than ever are building towards genuine financial resilience in later life. Change must happen faster. Too many women face a retirement of financial hardship, with life events such as unpaid caring responsibilities, menopause and relationship breakdowns disrupting their ability to save.”
Meanwhile, Scottish Widows retirement expert, Susan Hope, argued that addressing the gender pension gap would require wider changes to workplace practices and pension policy.
“Our data shows that the pension gap takes root from a woman’s very first job,” she noted.
“But closing it requires more than better awareness – it means fundamentally changing the systems that shape women’s financial futures. From pension enrolment and parental leave to support through divorce, menopause and illness, policy and workplace changes must better reflect women’s lives and help them build financial security at every stage.”
In response to the findings, Scottish Widows called for further reforms to AE, greater consideration of pensions in divorce settlements, and improved support for women facing changes in employment or caring responsibilities. The provider also urged employers to use pension scheme data to identify savings gaps early, improve financial education among younger workers and encourage greater sharing of caring responsibilities between men and women.


